The Employees’ Provident Fund Scheme, 2026 replaced thirteen withdrawal provisions with three. The two figures in the headlines describe the same rule.
Search for the new EPF withdrawal rules 2026 and you will find two different numbers. Some reports say you can now take out 100 percent. Others say 75 percent. Both are describing the same provision. The government notified the Employees’ Provident Fund Scheme, 2026 on 29 June 2026, replacing the 1952 scheme.
Where the Two Numbers Come From
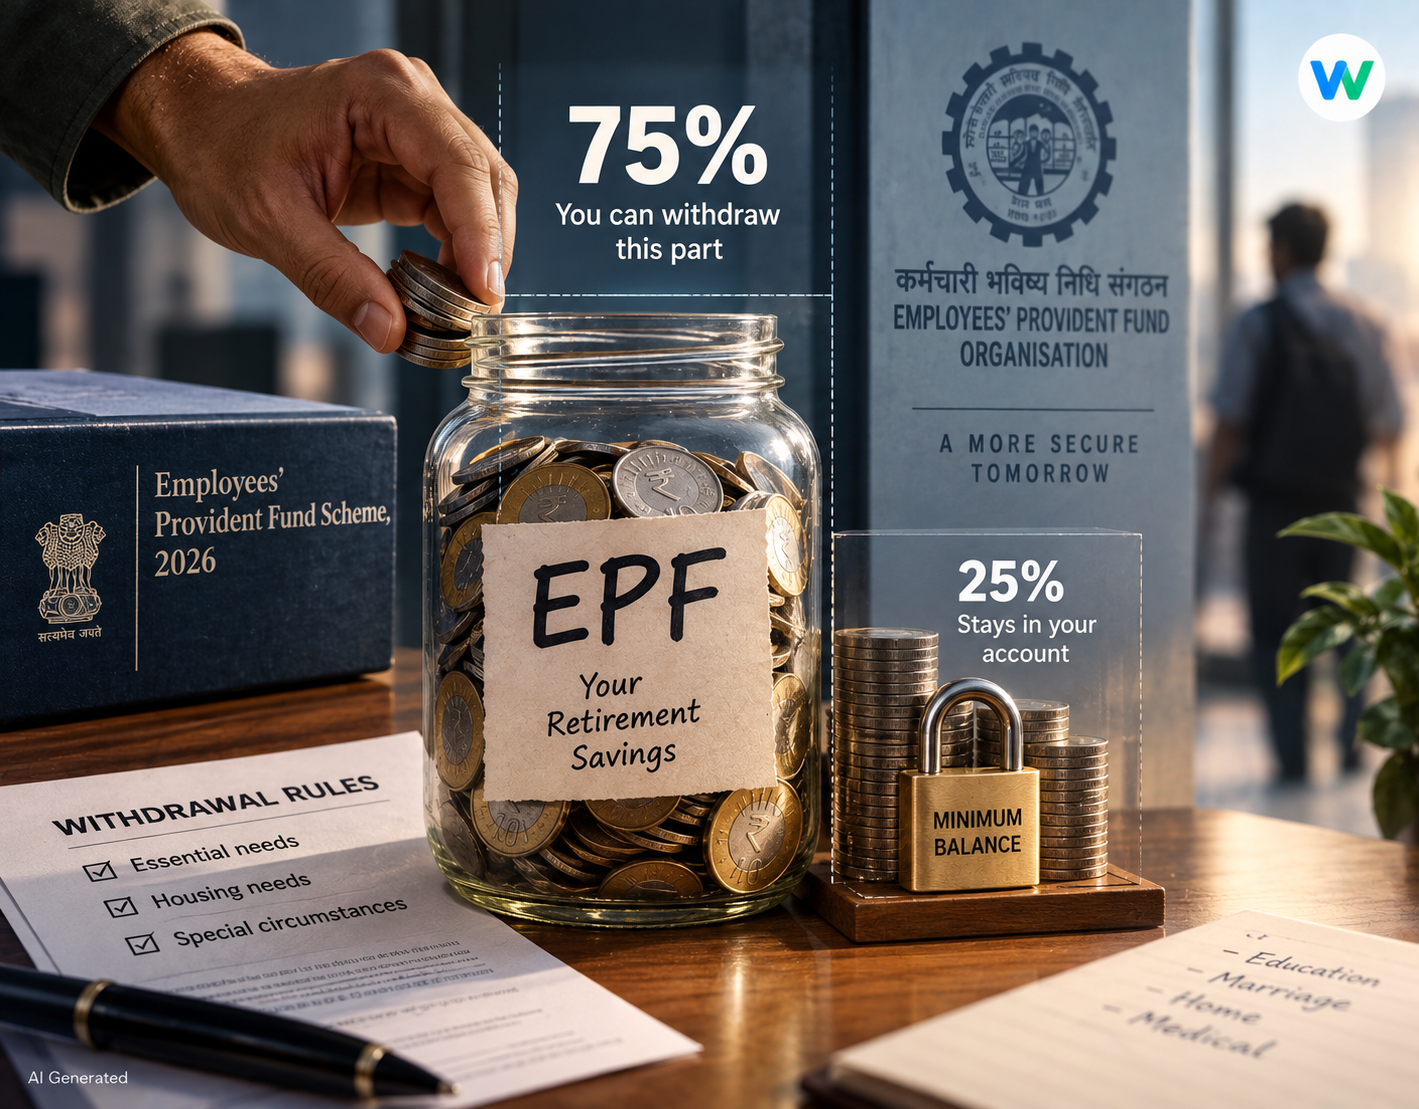
Paragraph 46 of the scheme settles it. A quarter of your balance has to stay in the account after any partial withdrawal. The scheme calls that quarter the Minimum Balance. It counts your contribution, your employer’s contribution, and the interest earned on both. What sits above it is the Eligible Member Balance. You can draw all of that.
So take a corpus of Rs 1 lakh. Rs 25,000 stays. Rs 75,000 can come out. The smallest withdrawal allowed is Rs 1,000.
That is 100 percent of the eligible balance. It is also 75 percent of the total. The reports saying 100 and the reports saying 75 are counting from different starting points. Neither is wrong.
Thirteen Reasons Became Three Under the EPF Withdrawal Rules 2026
The Central Board of Trustees merged thirteen withdrawal provisions into three headings. Essential needs covers illness, education and marriage. Housing needs covers buying, building, loan repayment and repairs. Special circumstances is the third.
The minimum service requirement is now twelve months for almost every category. It used to run to several years, depending on why you were withdrawing.
You can now withdraw for education up to ten times, for marriage up to five and for housing up to five. The old limit was three. Illness carries no cap on how often you can draw. Special circumstances allows two withdrawals in a financial year.
The Waiting Periods That Came With It
Closing your EPF account entirely now carries a twelve month wait. It used to be two months. The pension withdrawal under the Employees’ Pension Scheme carries thirty six months, up from two.
So the rules pull in two directions at once. Getting at part of your money got easier. Getting at all of it got harder.
Job loss falls under the same framework. Government statements have described 75 percent as available a month after your job ends, with the rest later.
The Wise Take
The headline number in a rule change is rarely the useful part. That holds for the EPF withdrawal rules 2026 as much as anything else. Here the useful part is the shape of the trade. You get easier access at the front and a longer wait at the back, and a quarter of your corpus stays put and keeps earning interest at 8.25 percent a year.
Whether that helps depends entirely on you. If you are drawing on the fund to cover a hospital bill, it is a real improvement. If you planned to move the whole balance out when you left a job, it is a restriction. Other savings rules have changed this year too. The notified scheme settles which applies to you, not the coverage of it, so read the gazette notification before you act.