Indians are investing through SIPs like never before. In September 2026, monthly SIP contributions touched a record ₹32,490 crore, and about 10.06 crore SIP accounts contributed. However, many of us still pick funds by popularity. A better path starts when you align mutual fund investments with financial goals.
Why You Should Align Mutual Fund Investments With Financial Goals
Let’s start with a simple truth. A fund is only a tool, and tools work best with a purpose. If you align mutual fund investments with financial goals, you stop chasing last year’s toppers. Instead, you ask a better question: what is this money for? Many beginners make the same mistake. They invest in whatever looks popular on social media or in a friend’s chat. However, a fund that suits your friend may not suit your timeline or your comfort with risk.
Think of it like packing for a trip. A weekend getaway needs a small bag. A year abroad needs a big suitcase. Similarly, a holiday next year and retirement in thirty years need very different funds. Without a goal, you may also panic at the wrong time. When markets fall, a goal gives you a reason to stay calm. As a result, you act on a plan instead of fear.
Name Each Goal and Give It a Deadline
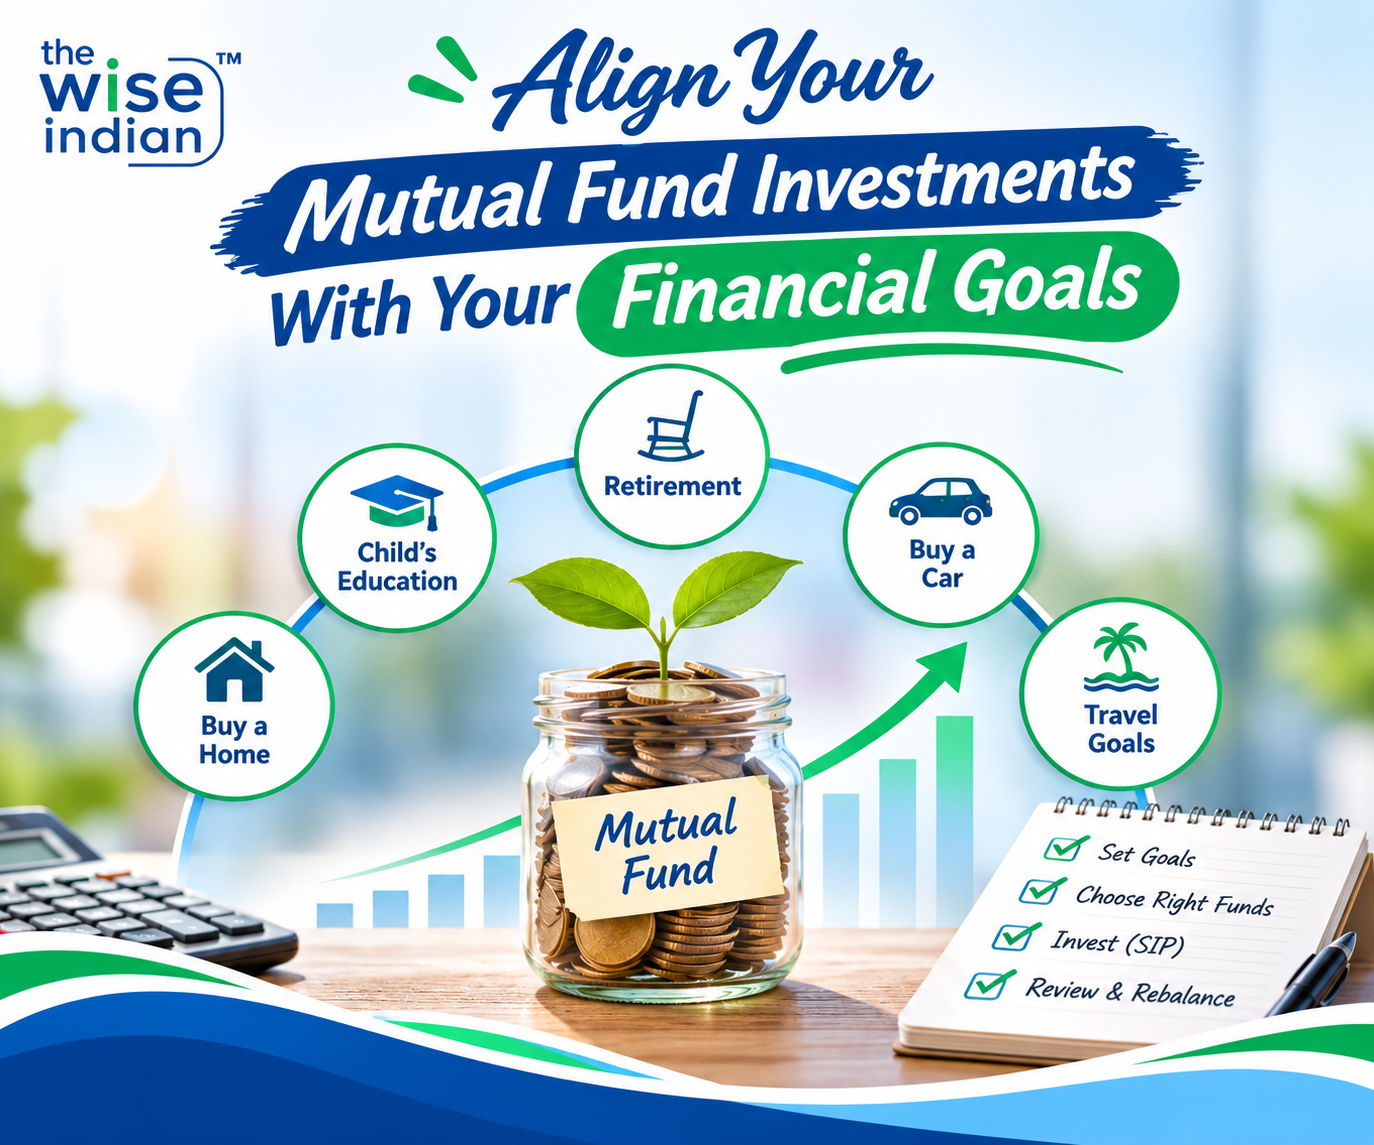
First, write down what you want. Be specific. “Save money” is vague, but “buy a ₹10 lakh car in five years” is clear. Next, attach a rough amount and a date to every goal. Write these in a notebook or a phone note. Then sort your goals into three buckets. Short-term goals fall within three years, such as a holiday or an emergency fund. Medium-term goals take three to seven years, like a house down payment. Long-term goals run beyond seven years, such as retirement or a child’s education.
Also, think about inflation. Costs rise every year, so tomorrow’s goal needs a bigger number than today’s price tag. For example, a ₹10 lakh goal today may cost more in five years. Therefore, add a cushion to your target. Finally, build an emergency fund before anything else. Many planners suggest three to six months of expenses. Keep it in a safe, easy-to-access place, so you never break a long-term investment in a crisis.
Match Each Goal to the Right Fund Type
Now comes the fun part. Your timeline decides your fund type. Generally, the shorter the goal, the lower the risk you should take. Meanwhile, longer goals can handle more ups and downs. For goals under three years, consider liquid or short-duration debt funds. They aim for stability, not big gains. For medium goals, a hybrid fund can balance growth and safety. For long goals, equity funds, such as index or flexi-cap funds, have more room to grow. To help you compare, SEBI groups schemes into clear categories, such as equity, debt, and hybrid. That way, you compare like with like. Besides, each scheme’s factsheet lists its holdings and risks.
However, always check the riskometer before you invest. SEBI requires every scheme to show one. It has six levels, from Low to Very High, and fund houses typically reassess it every month. A high-risk fund for a one-year goal is a mismatch, no matter how good its past returns look. Also, remember that past returns never guarantee future ones. Equity funds can fall sharply in the short run. So, give them time, and keep the money you need soon in safer funds. That is how you align mutual fund investments with financial goals in practice.
Invest Steadily, Mind the Tax, and Review Yearly
Next, choose how you invest. A SIP lets you invest a fixed amount every month, so you build the habit automatically. Moreover, it spreads your buying across market highs and lows. Some people even keep a separate fund for each goal. That way, you never mix up your holiday money with your retirement savings. A lump sum can work too, especially when you receive a bonus. However, for beginners, SIPs feel easier and less stressful. Additionally, increase your SIP a little each year as your income grows. This step keeps your plan on track against inflation.
Costs matter as well. Direct plans charge a lower expense ratio than regular plans because they skip distributor commission. Over many years, that small gap adds up. So, compare expense ratios before you finalise a fund. Tax also shapes your take-home gains. If you hold equity funds over one year, gains above ₹1.25 lakh per financial year face 12.5% tax. Budget 2026 did not change these rates for FY 2026-27. Therefore, plan your withdrawals with this limit in mind. Finally, review your plan once a year. Check whether your goals, income, or timelines have changed. If a goal is two or three years away, shift some money from equity to safer funds. Meanwhile, avoid checking returns daily, because that only adds stress.
The Wise Take
In the end, mutual funds are not about beating the market. They are about reaching your own finish line. So, name your goals, set deadlines, and pick funds that fit each timeline. Start small if you must. Even a modest SIP with a clear goal beats a big investment with no purpose. When you align mutual fund investments with financial goals, every rupee gets a job. Consequently, market noise bothers you less. Remember, markets rise and fall, but a clear goal keeps your plan steady through both. This is for educational purpose, not a personal advice
Also read our other article on Gold, Digital Gold, Gold ETFs or Sovereign Gold Bonds: Which One Should You Choose Before Dhanteras This Year in India?
Follow The Wise Indian for clear, unbiased, and actionable guides that make personal finance simple.