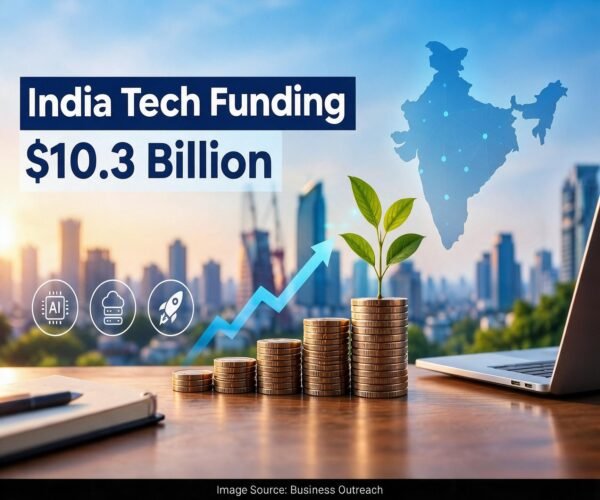
The story of Indian tech funding in 2026 is not one of a market shrinking. It is one of a market growing up. In the first nine months of the year, Indian tech startup raised $10.3 billion. That is a 7% increase over the same period last year. It is also 3% higher than what was raised in the first nine months of 2024. The headline number tells you capital is still flowing.
But look closer. The number of funding rounds has fallen from 1,838 to 1,134. That is a 38% drop. First-time funded companies are down 30% to just 338. Seed funding has fallen 37% to $698 million. The pipeline at the very top is thinning. And yet, the dollars are up.
This is the paradox of the 2026 funding cycle. It is not that startup investors have stopped writing cheques. They have simply decided to write fewer, larger ones, to companies they already believe in.
The Mega-Round Era
The concentration is stark. Eighteen rounds of $100 million or more were recorded in the first nine months of 2026. These are the deals that carried the entire year. Nxtra, a data-centre business, raised $1 billion in private equity. Neysa, an AI cloud platform, raised $600 million. CRED raised $540 million. Brahma AI raised $150 million at a $2 billion valuation. Ultraviolette, an electric motorcycle maker, raised $85 million.
These are not speculative bets on unproven ideas. These are cheques written for companies with products, revenue, and a clear path to scale. The market is rewarding execution, not just ambition.
Where the Money Is Going
The sectoral shift is equally revealing. Enterprise infrastructure saw funding surge by 436% to $1.6 billion, up from just $292 million a year earlier. This is the plumbing of the AI economy, computing power, data centres, and the backend systems that make artificial intelligence work at scale. AI infrastructure alone was the single most-funded business segment in startup, attracting $1.2 billion.
Enterprise applications grew 49% to $3.5 billion, and fintech rose 13% to $2.2 billion, with digital lending and payments leading the charge.
The message is clear. Investors are not chasing consumer apps with big user numbers and no revenue. They are backing the infrastructure and enterprise software that power the broader economy. This is a more mature, more disciplined phase of Indian tech.
This shift is not unique to India. Global venture capital is also concentrating in AI infrastructure and enterprise software, leaving consumer apps and early-stage startups to fend for themselves. But India’s advantage lies in its cost-efficient engineering talent and its vast domestic market. The companies that can combine both will be the ones that attract the mega-rounds. The $10.3 billion is not a ceiling. It is a floor for what is possible.
The Seed Stage Is Hurting
While the headline numbers look healthy for startup, the pain remains concentrated at the earliest stages. Seed funding fell 37%. The number of first-time funded companies dropped to 338. Series A and later rounds fell 23%.
This means it is harder than ever to secure that first cheque. Founders just starting out face a tougher market than those who raised their first round two or three years ago. The bar has risen for startup. Investors want proof, not potential.
What This Means for Founders
If you are a founder building in 2026, the rules have changed. The days of easy seed capital are over. You need to show traction earlier. You need a story that is backed by numbers, not just vision.
But there is a flip side. If you can demonstrate that you are building something real, the capital is there. The mega-rounds show that investors are willing to deploy large sums for companies that have proven they can execute. The bar is higher, but the reward is bigger.
The Maturity of the Ecosystem
Perhaps the most telling metric is the speed at which companies are reaching exit. The average time from first funding to an IPO has fallen from 13.7 years to 8.5 years. The average time to acquisition has dropped from 14.7 years to 6.9 years.
This is what a maturing ecosystem looks like. Companies are growing faster, exiting sooner, and returning capital to investors who can then redeploy it into the next generation of startups. The cycle is shortening.
India minted six new unicorns in the first nine months of 2026, up from four a year earlier. But founders built these unicorns with less capital. They raised an average of $101 million before reaching unicorn status, compared to $205 million the year before.
They are doing more with less. That is not a sign of weakness. It is a sign of efficiency.
The Wise Take
The Indian tech ecosystem is not in a downturn. It is in a transition. The era of cheap money and endless seed rounds is over. What is emerging is a more selective, more disciplined market where capital flows to the companies that deserve it.
For the founders who can navigate this, the opportunity is enormous. The infrastructure is being built. The enterprise software is being adopted. The fintech rails are being laid. The companies that build on top of this foundation will be the ones that define the next decade.
The $10.3 billion is a signal. The money is still here. It is just looking for better homes.
For more such articles, keep reading The Wise Indian.